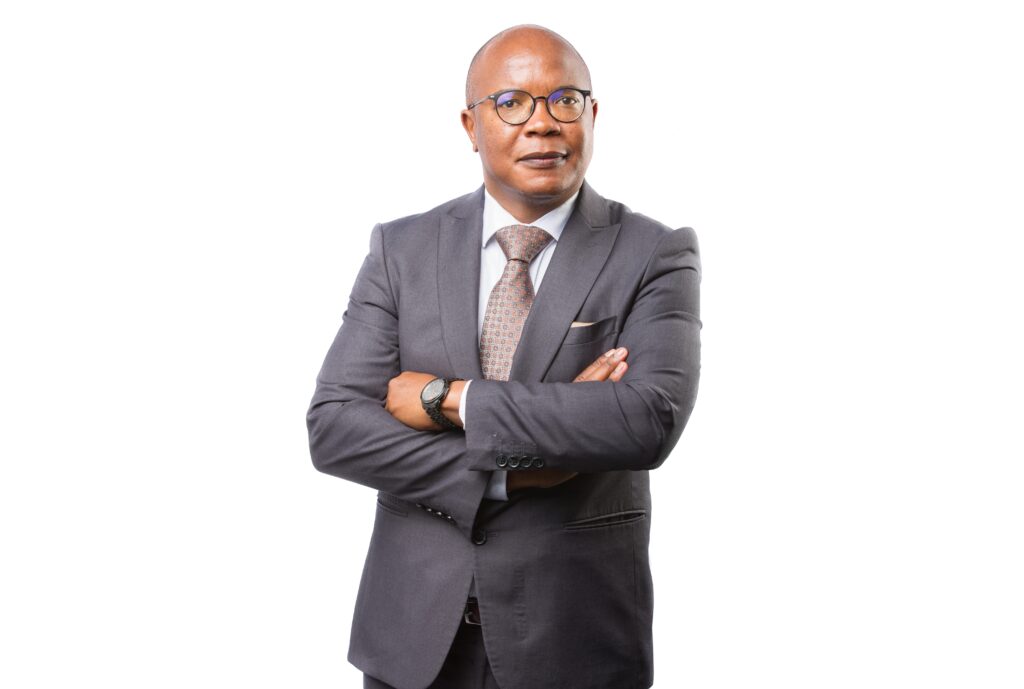
Seen Here: Samukelo Zwane, Head of Product at FNB Wealth and Investments. Photo Credit: Supplied
FNB Retirement Insights Survey 2026 highlights the growing pressure on retirees to balance family financial obligations with their own long-term security.
JOHANNESBURG, 20 October 2026 — Retirement is traditionally viewed as the reward for decades of hard work, disciplined saving and financial planning. However, for an increasing number of South African pensioners, life after employment is bringing a different challenge: using retirement income and accumulated savings to help adult children navigate financial emergencies.
From covering unexpected household expenses and contributing towards grandchildren’s education to assisting financially strained family members, retirees are increasingly finding themselves supporting multiple generations. This places additional pressure on retirement funds that were intended to provide financial stability during the later stages of life.
The trend highlights a growing dilemma for South African households: how can retirees remain financially secure while continuing to fulfil deeply rooted family responsibilities in an economy where financial pressures affect younger and older generations alike?
The FNB Retirement Insights Survey 2026: Understanding South Africans’ Retirement Preparedness identifies breaking the cycle of dependency as one of the key themes influencing retirement outcomes. Although many South Africans aspire to retire without becoming financially dependent on their children, the findings point to a more complex reality — retirees themselves often continue providing financial assistance to family members long after leaving the workforce.
As living costs rise and financial recovery becomes increasingly difficult for some households, retirement income is taking on a broader role, serving not only as a source of personal security but also as a financial safety net for extended families.
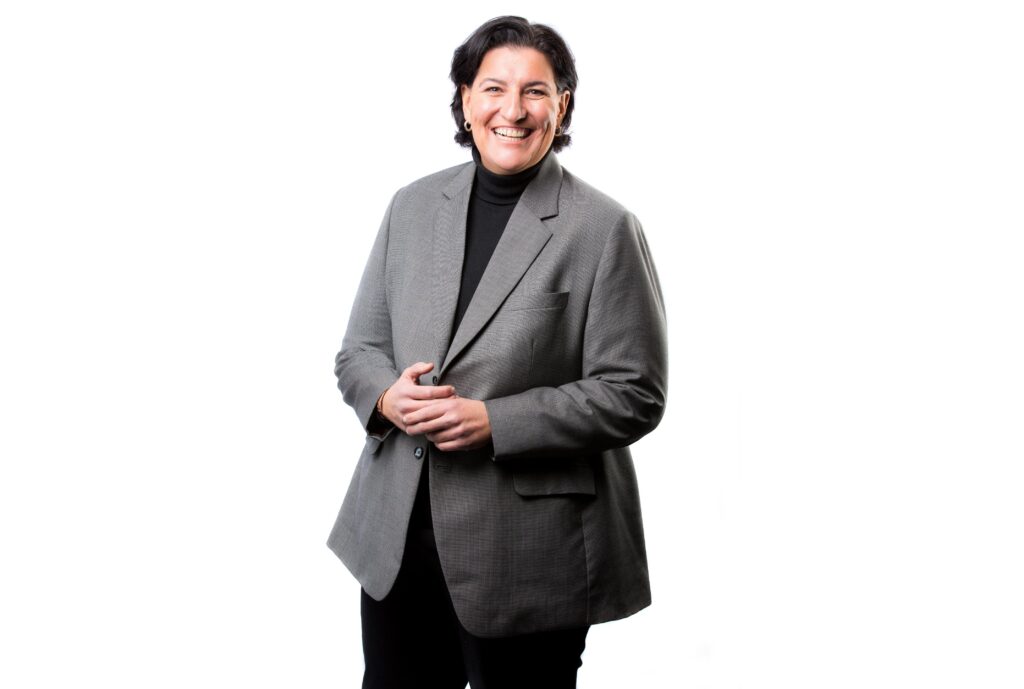
Seen Here: Ester Ochse, Product Head at FNB Integrated Advice. Photo Credit: Supplied
Family responsibility versus financial security
According to Ester Ochse, Product Head of Integrated Advice at FNB, retirement is increasingly being shaped by the wider economic pressures facing South African households.
“Supporting family members is deeply embedded in South Africa’s social fabric, and for many retirees, helping loved ones through difficult periods is not a financial decision, it’s a personal one,” says Ochse.
However, she warns that temporary assistance can gradually develop into a long-term financial commitment, potentially undermining the very security retirees spent decades building.
“When retirees repeatedly draw on income and savings intended to fund their own future, they risk compromising their financial security, reducing their ability to absorb unexpected expenses, and placing additional pressure on resources that may need to last for decades,” she explains.
Balancing family support with personal financial security is therefore becoming an increasingly important consideration in retirement planning.
For pensioners living on fixed or limited incomes, the consequences of consistently supporting financially dependent relatives can be particularly significant. Every withdrawal from retirement savings may reduce the funds available for future living expenses, healthcare needs and unforeseen emergencies.
The multigenerational financial squeeze
The financial strain is not limited to retirees. Younger South Africans are also navigating rising household costs, financial uncertainty and unexpected expenses, creating circumstances in which family members may turn to older relatives for assistance.
Samukelo Zwane, Head of Products at FNB Wealth and Investments, says the survey highlights how financial pressures are affecting entire families rather than only those who are still employed.
The resulting decisions can be difficult: pensioners must weigh the immediate needs of loved ones against the importance of preserving savings that may need to sustain them for many years.
In some households, the pension has effectively become a shared financial resource, helping to stabilise family budgets when other sources of income fall short.
While this support can provide essential relief, it also raises questions about the sustainability of informal family support systems when the people providing assistance have limited opportunities to replenish their savings.
Retirement planning, traditionally focused on an individual’s expected lifespan, income requirements and healthcare expenses, must increasingly account for the possibility of supporting children, grandchildren and other relatives.
Helping without compromising retirement
Financial assistance does not necessarily have to come at the expense of retirement security. However, FNB emphasises the importance of making informed decisions before committing money to family members.
Retirees should consider two critical questions before providing financial support.
1. Can I afford to help without compromising my future needs?
Retirement income, healthcare provision and emergency savings should remain priorities. Pensioners need to assess whether financial assistance will leave them with sufficient resources to cover their own essential expenses and unexpected costs.
2. Will this assistance create a path towards financial independence?
Where possible, support should help family members address the underlying causes of financial difficulty rather than create a cycle of ongoing dependence. This may involve helping them develop a budget, manage debt, improve their financial planning or identify more sustainable sources of income.
Clear boundaries and open family conversations can also help establish realistic expectations about what retirees can afford to contribute.
Importantly, the objective is not to discourage generosity. It is to ensure that assistance is provided in a way that protects the financial wellbeing of both the person receiving support and the person providing it.
Financial advice becomes increasingly important
As retirement responsibilities evolve, access to professional financial guidance can help pensioners assess the long-term consequences of their decisions and identify sustainable ways to support their families.
FNB points to solutions such as My Advisor on the FNB App, which gives customers access to personalised financial guidance, alongside products such as the FNB Retirement Annuity, which can form part of a broader strategy for building long-term retirement security.
The suitability of any financial product will depend on an individual’s circumstances, existing retirement arrangements and financial objectives. Retirees should therefore consider their overall financial position before making decisions that could affect their future income.
For financial institutions and retirement planners, the challenge is increasingly to recognise that retirement decisions rarely happen in isolation. Family obligations, healthcare costs, household expenses and longevity all influence how effectively retirement resources can meet future needs.
Redefining retirement security
“Many people enter retirement expecting their financial responsibilities to gradually ease after years of disciplined saving and planning. Yet increasingly, retirees are finding themselves supporting not only their own needs, but those of children, grandchildren and extended family members as well,” says Ochse.
She adds that financial security and family support do not have to be mutually exclusive, provided retirees approach assistance with careful planning and a clear understanding of their financial limits.
The emerging retirement reality presents a broader lesson for South African households: preparing for retirement must involve more than calculating how much money will be needed after leaving the workforce. It must also consider the financial responsibilities that may continue, or even intensify, during retirement.
Ultimately, a sustainable approach requires a balance between compassion and financial discipline. By setting clear boundaries, encouraging financial independence among family members and seeking appropriate financial advice, retirees can continue supporting their loved ones without unnecessarily jeopardising the future they worked so hard to secure.
#RetirementPlanning #FinancialWellness #RetirementSecurity #FNB #FNBRetirementInsights #PersonalFinance #FinancialLiteracy #WealthManagement #Pensioners #SouthAfricanEconomy #FamilyFinances #MultigenerationalWealth #FinancialIndependence #BusinessNews #CommunityNewsroom