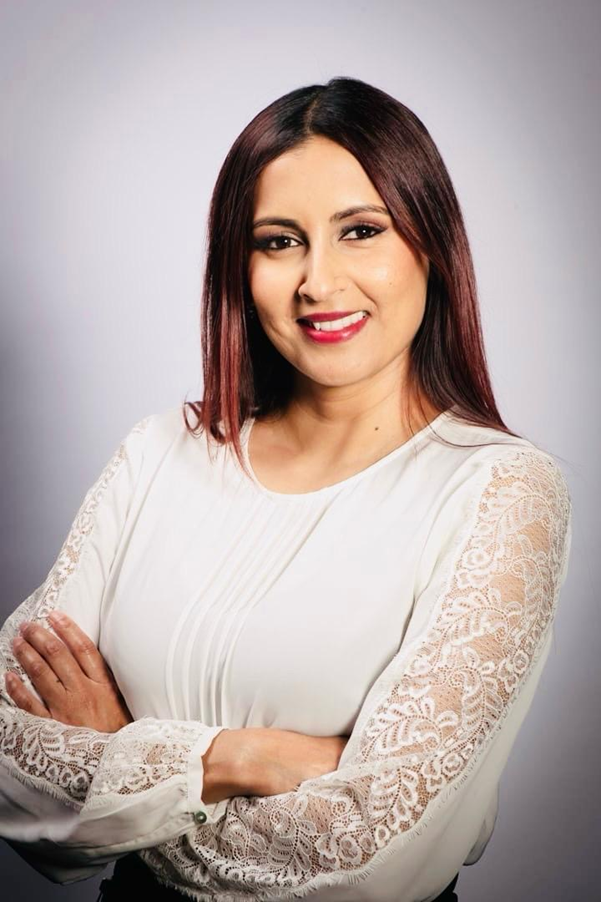
Seen Here: Vanashree Naidoo, FNB Home and Structured Lending Product Head, shares insights into how South Africans are rethinking homeownership as they plan for retirement. Photo Credit: Supplied
Older homeowners are opting for smaller properties, sectional-title living and greater financial flexibility as retirement reshapes their housing priorities.
For generations, owning a home has been regarded as one of the clearest symbols of financial security. But as more South Africans approach retirement, a growing number are rethinking what homeownership should look like in their later years.
New data from FNB Home and Structured Lending suggests that the focus is shifting from owning a larger property to finding a home that offers greater convenience, manageable costs and the financial freedom to enjoy retirement.
Drawing on South African property transaction trends and customer data between 2015 and 2025, the bank’s analysis reveals that older buyers are becoming an increasingly significant part of the property market, with many choosing to downsize or move into more manageable homes as their needs change.
The proportion of property buyers aged 56 and older rose from 14% in 2015 to 19% in 2025. Repeat buyers now account for 70% of senior buyers, compared with 56% a decade ago.
The figures point to a generation of older homeowners taking a more deliberate approach to property decisions, weighing the value of their existing homes against the realities of retirement.
Vanashree Naidoo, Product Head of Home and Structured Lending at FNB, says retirement is prompting homeowners to reconsider whether their properties remain suited to their changing lifestyles and long-term financial goals.
Downsizing gains momentum among older homeowners
One of the clearest trends emerging from the data is the growing preference for smaller homes.
Among senior homeowners who sold a property and subsequently bought another, the proportion purchasing a smaller home increased from 54% in 2015 to 62% in 2025.
The inclination to downsize also increases with age. While 50% of homeowners aged 55 to 59 opted for a smaller property, that figure climbed to 71% among those aged 80 and older.
The shift reflects a broader reassessment of what makes a home suitable for retirement. Larger properties may offer space and long-term sentimental value, but they can also bring higher maintenance costs, greater security responsibilities and more demanding upkeep.
For retirees living on a fixed or reduced income, these expenses can place additional pressure on household finances.
Rightsizing, however, is not simply about moving into a smaller home. It is about choosing a property that better supports an individual’s financial circumstances, lifestyle preferences and future needs.
“Rightsizing doesn’t necessarily mean settling for less,” says Naidoo. “For many retirees, it’s about finding a home that better aligns with the lifestyle they want to enjoy in their golden years.”
That could mean spending less time maintaining a property, reducing monthly expenses, improving security or moving closer to family, healthcare facilities and essential services.
Sectional-title properties attract growing interest
The type of property older buyers choose is also changing.
FNB’s analysis shows that the proportion of properties purchased exclusively by senior buyers that were freehold homes declined from 75% to 66% over the period under review.
This suggests a growing interest in alternatives such as sectional-title developments, which can offer shared maintenance arrangements, enhanced security and the convenience of lock-up-and-go living.
For people entering retirement, these features can become increasingly attractive as priorities shift away from managing a large property towards spending more time on travel, family, hobbies and other personal pursuits.
However, sectional-title living is not automatically cheaper. Levies, special levies, complex rules and the financial health of a body corporate remain important considerations for prospective buyers.
The key is to assess the total cost and practicality of a property rather than focusing solely on its purchase price or size.
Retirement does not always mean being mortgage-free
While many older South Africans purchase property without a home loan, FNB’s findings highlight another important consideration: retirement does not necessarily eliminate housing debt.
Although fewer retirees have active home loans today than a decade ago, the average and median outstanding balances among those who still have mortgage debt have increased.
For homeowners approaching retirement, this makes it particularly important to understand how a property decision could affect their financial position over the long term.
Selling a larger home may release equity, but the proceeds are not necessarily equivalent to the property’s full market value. Estate agent fees, legal expenses, moving costs and the price of a replacement home can all affect how much money remains available.
Homeowners who intend to buy another property should also consider whether they will need financing and whether repayments would remain affordable after retirement.
Naidoo advises homeowners to assess their available equity, transaction costs, future affordability and evolving housing needs before deciding whether to sell or stay.
A property can play a significant role in retirement planning, but its value should be considered alongside other assets, income sources and expected expenses.
Why location matters more in retirement
Where retirees choose to live remains another important factor.
According to FNB’s analysis, the Western Cape attracted the highest number of senior property purchasers during the period studied. It also retained the majority of senior homeowners who sold and bought another property within the province.
Although lifestyle preferences vary, the findings point to the importance of location when making long-term housing decisions.
Access to healthcare, reliable transport, family networks, shopping facilities and established communities can all influence whether a property remains suitable as homeowners grow older.
A location that works well during a person’s working years may become less practical once commuting requirements change or access to medical services becomes a greater priority.
Affordability also extends beyond the purchase price. Municipal rates, utilities, insurance, levies, transport costs and ongoing maintenance can significantly affect the long-term cost of living in a particular area.
For this reason, choosing a retirement home requires a broader assessment of both the property and the lifestyle it makes possible.
Should homeowners sell before retirement?
FNB’s findings do not suggest that every homeowner should downsize. Instead, they highlight the value of reviewing property decisions before retirement places additional pressure on household finances.
For some people, remaining in a familiar home may be the most practical and financially sound option, particularly if the property is paid off, accessible and affordable to maintain.
For others, selling and moving to a smaller property could release equity, reduce upkeep and provide greater flexibility in retirement.
The right decision will depend on individual circumstances, including pension income, savings, outstanding debt, family commitments, health considerations and future lifestyle expectations.
Homeowners should also consider whether a move today will continue to meet their needs in 10 or 20 years, rather than focusing exclusively on their current circumstances.
Naidoo says the most effective property decisions are those made proactively, with both lifestyle aspirations and long-term financial objectives in mind.
“Retirement presents an opportunity to reassess what matters most and ensure that your home continues to support the life you want to lead,” she says.
“Whether that means remaining in your current property, downsizing or rightsizing, the key is to make a decision that aligns with your lifestyle needs, financial goals and future priorities.”
A new definition of homeownership
The latest figures suggest that, for an increasing number of older South Africans, property ownership is becoming less about the size of the home and more about how effectively it supports their next stage of life.
With senior buyers accounting for a growing share of the market and more older homeowners choosing smaller properties, retirement planning is increasingly influencing housing decisions.
The lesson for those approaching retirement is straightforward: owning a valuable property can provide financial security, but that security also depends on whether the home remains affordable, practical and appropriate for the years ahead.
Rather than waiting until retirement forces a change, homeowners may benefit from assessing their options early, understanding the financial implications of moving and deciding what they want their property to deliver.
Ultimately, the goal is not necessarily to own less, but to make homeownership work better for the life that lies ahead.
#SouthAfrica #Homeownership #RetirementPlanning #PropertyMarket #FNB #FinancialFreedom #RealEstateSA #WealthBuilding