
FNB urges consumers to rethink everyday digital habits as sophisticated scams exploit trust, urgency and financial pressure
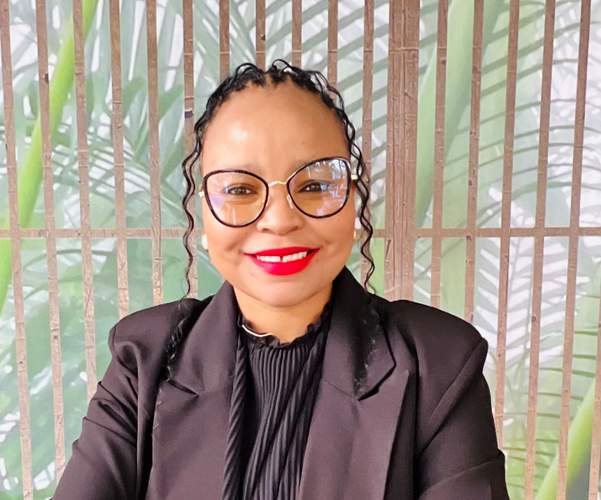
Seen Here: Moshibudi Sebola, Consumer Education Operations Support Manager at FNB, urges consumers to stay vigilant as fraudsters become increasingly sophisticated, using trusted digital platforms, impersonation and AI-driven tactics to deceive victims. She emphasises the importance of pausing, verifying and thinking twice before clicking, paying or sharing sensitive information. Photo Credit: Supplied
JOHANNESBURG, 10 September 2026 — Financial resilience in South Africa increasingly means more than budgeting, saving and managing household expenses. As fraudsters become more sophisticated, consumers are also being urged to develop stronger habits around protecting their money and digital identities.
The warning comes as South Africa’s banking sector continues to face a rapidly evolving digital-fraud environment, with criminals exploiting trusted platforms, social engineering and increasingly convincing artificial-intelligence-generated content to manipulate consumers.
The South African Banking Risk Information Centre (SABRIC) has identified digital banking fraud as a dominant component of the country’s financial-crime landscape. Its latest reporting also highlights the growing use of AI-generated phishing, cloned messages and deepfake technology to make fraudulent communications appear increasingly authentic.
For consumers already dealing with the pressures of rising living costs, unexpected expenses and financial uncertainty, the challenge is particularly acute.
A seemingly attractive discount, job opportunity, investment proposition, refund or urgent financial offer can create exactly the emotional response fraudsters are seeking.
“Being financially savvy today is about more than budgeting or saving for the future. It also means understanding how fraudsters operate and recognising when something that seems familiar or legitimate deserves scrutiny,” says Moshibudi Sebola, Consumer Education Operations Support Manager at FNB.
1. Fraud is moving into trusted digital spaces
One of the biggest challenges facing consumers is that fraudulent activity is increasingly appearing within environments they already recognise.
A legitimate website, app or social-media platform does not necessarily mean that every seller, advertisement or interaction taking place on it is legitimate.
Fraudsters can exploit established digital platforms to create fake seller profiles, advertise attractive products or redirect consumers towards fraudulent payment arrangements.
SABRIC has similarly warned consumers about fake online stores, cloned websites, fraudulent advertisements and payment requests designed to exploit the trust associated with recognised brands and platforms.
“Consumers should avoid assuming that a familiar website or app automatically makes every interaction safe,” warns Sebola.
Before making an online purchase, consumers should check seller reviews and ratings where available, be cautious about unusually attractive offers and avoid making payments outside a platform’s normal payment process.
The principle is straightforward: familiarity should never replace verification.
2. Protecting account access is becoming critical
Fraudsters are also increasingly targeting access to consumers’ existing accounts.
Account-takeover schemes can involve stolen credentials, phishing links, malicious applications or social-engineering tactics designed to persuade victims to authorise transactions themselves.
The threat is evolving beyond simply stealing passwords.
SABRIC has warned about remote-access trojan attacks, in which criminals can gain control of a victim’s device after persuading them to install malicious software disguised as a legitimate security, verification or other application. Once installed, such software can allow criminals to view screens, capture credentials and facilitate fraudulent transactions.
This makes protecting the device itself just as important as protecting the bank account.
Consumers should use strong and unique passwords, activate additional security features where available, keep operating systems and applications updated and avoid installing software at the request of an unsolicited caller or message.
Unexpected login notifications, device-verification requests or transaction-approval prompts should also be treated with caution.
If a message appears to originate from a bank, government department, retailer or service provider, consumers should avoid using embedded links and instead contact the organisation directly through independently sourced contact details.
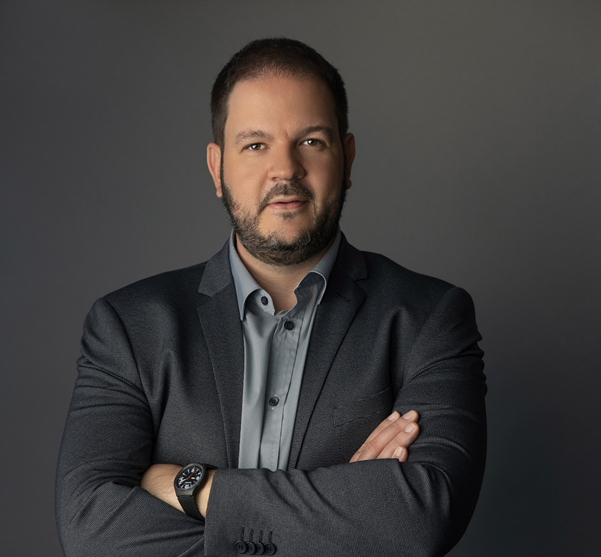
Seen Here: Ettienne Fourie, FNB Retail’s Head of Fraud, urges consumers to slow down, verify and think twice before responding to suspicious messages, clicking links or approving transactions. As fraudsters become increasingly sophisticated, a few moments of caution can make the difference between protecting your money and falling victim to a scam. Photo Credit: Supplied
3. AI is making scams harder to recognise
The traditional warning signs of fraud are becoming less reliable.
Poor spelling, awkward wording and obvious design flaws once provided useful clues. Artificial intelligence is now helping criminals produce professional-looking messages, realistic impersonations and highly convincing social-engineering campaigns.
SABRIC has warned that AI is being used to create error-free phishing communications, WhatsApp messages and voice-based deepfakes capable of impersonating trusted individuals.
The implication is significant: consumers can no longer rely solely on how convincing a message looks or sounds.
Instead, attention needs to shift to what the communication is asking the recipient to do.
Requests for passwords, PINs, one-time passwords, confidential information, urgent payments or transaction approvals should trigger additional verification — regardless of how legitimate the communication appears.
“Today’s scams are carefully designed to look legitimate and to catch consumers off guard,” says Ettienne Fourie, Head of Fraud for Retail and Business Banking at FNB.
“Fraud prevention starts with slowing the process down. If someone is pushing you to act immediately, share information or approve a payment, take a moment to pause and confirm who you are dealing with. A few extra minutes could prevent significant financial loss,” he says.
The psychology behind the scam
Technology may be changing the tools available to criminals, but the underlying strategy remains deeply human.
Fraudsters exploit emotions.
Fear, greed, urgency, excitement and desperation can all weaken a person’s willingness to stop and verify information.
This is why financial pressure can make consumers particularly vulnerable. A job offer promising immediate income, an investment promising exceptional returns, a large discount or an unexpected refund may appear especially attractive when household finances are under strain.
SABRIC’s guidance similarly emphasises the importance of resisting pressure tactics and verifying requests independently rather than acting immediately.
“One of the biggest misconceptions about fraud is that it only affects people who are careless,” says Fourie.
“The reality is that today’s scams are carefully designed to look legitimate and to catch consumers off guard.”
The new rules of digital financial safety
For consumers, the evolving fraud landscape means that basic financial literacy now needs to incorporate digital-security literacy.
That means understanding not only how to budget and save, but also how to recognise manipulation, protect account credentials and verify digital communications.
Some of the most effective habits are also among the simplest:
- Pause before acting when a request creates urgency.
- Never share PINs, passwords or OTPs, even with someone claiming to represent a bank.
- Verify independently rather than using contact details contained in an unsolicited message.
- Avoid clicking unexpected links in SMS, email or messaging applications.
- Never install software at the request of an unsolicited caller or message.
- Use strong, unique passwords and additional authentication features where available.
- Monitor account activity and report suspicious transactions immediately.
SABRIC’s consumer guidance similarly advises users to avoid unsolicited links, protect credentials, keep devices updated and contact their bank immediately if suspicious activity occurs.
Fraud prevention is part of financial wellbeing
The increasing sophistication of fraud means that protecting money is becoming an integral part of financial wellbeing.
For banks, this creates an ongoing responsibility to strengthen fraud detection, educate customers and develop security measures that can respond to increasingly sophisticated criminal techniques.
For consumers, it requires a corresponding behavioural shift.
Digital banking is not inherently unsafe. In fact, digital services have become fundamental to how millions of South Africans manage their finances.
The challenge is ensuring that convenience does not eliminate caution.
“Fraudsters are increasingly using the same channels and digital tools that consumers use every day,” says Sebola.
“Creating a simple habit of pausing before responding, clicking or paying can go a long way in protecting yourself from financial harm.”
As the distinction between genuine and fraudulent digital communication becomes increasingly difficult to identify at first glance, verification is emerging as one of the most valuable financial-security tools available to consumers.
The message for South Africans is therefore not to retreat from digital banking, but to use it more deliberately.
Protecting your money is no longer only about how you earn, spend, save or invest it. It is also about knowing when to stop, question and verify before someone else gets access to it.