
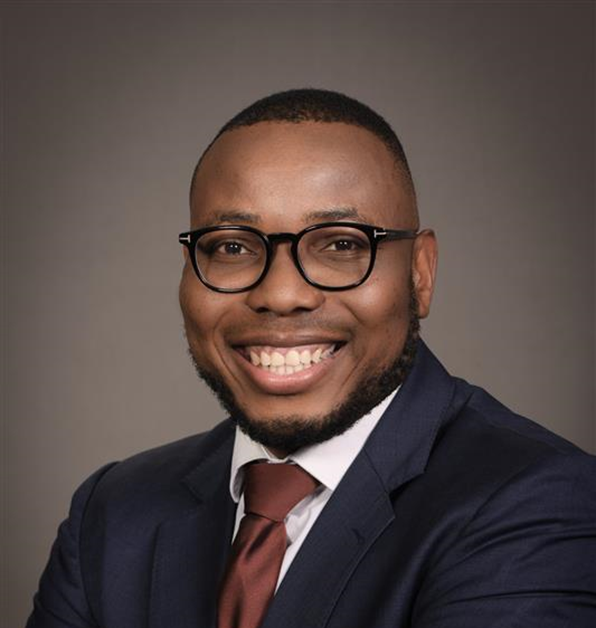
Seen Here: Thabiso Tshabalala, Credit Card Product Head at FNB, is championing a more responsible and informed approach to credit—one that goes beyond simply providing access. From understanding affordability and managing repayments to building a healthy credit record, responsible borrowing can become a powerful foundation for long-term financial resilience.Photo Credit: Supplied
Johannesburg, 22 September 2026 — As South Africa’s financial inclusion journey continues to broaden access to formal banking services, FNB says the next challenge is ensuring that customers can enter or re-enter the credit market responsibly, with the knowledge and support needed to build sustainable financial futures.
The call comes as increasing attention is being placed on the experiences of first-time credit users and consumers seeking to rebuild their credit profiles after periods of financial difficulty.
According to Thabiso Tshabalala, Credit Card Product Head at FNB, responsible financial inclusion should extend beyond simply making credit available.
“Access to credit is important, but access alone is not enough. The real question is how we create pathways that allow customers to build healthy, sustainable relationships with credit over time.”
Tshabalala says responsible lending should combine access with education, transparency, affordability assessments and ongoing customer support.
“Responsible lending isn’t simply about making credit available. It’s about helping customers understand it, manage it effectively and use it in ways that support their long-term financial wellbeing.”
Breaking the credit catch-22
For consumers with established credit histories, lenders can draw on years of repayment behaviour when assessing applications. First-time borrowers, however, face a different challenge because they have little or no credit history against which their behaviour can be evaluated.
Customers attempting to rebuild their financial profiles after previous difficulties can face a similar challenge.
Tshabalala describes this as a “credit catch-22”: consumers need an opportunity to demonstrate responsible credit behaviour in order to build a credit profile, but accessing that first opportunity can itself depend on having an established credit history.
“To build a credit profile, customers need an opportunity to demonstrate responsible credit behaviour. Yet, in many cases, one needs a credit profile before they can access that opportunity.”
For consumers returning to credit, he says financial institutions also need to consider their current circumstances while maintaining appropriate lending standards.
Responsible access remains critical
FNB stresses that expanding access should not mean relaxing affordability or creditworthiness requirements.
With many South African households continuing to navigate financial pressures, Tshabalala says credit should not be positioned as a remedy for financial distress.
“Affordability and creditworthiness assessments remain fundamental to responsible lending. Credit should never be positioned as a solution to financial distress.”
Instead, he says, financial institutions should focus on creating appropriate entry points for customers who qualify, while reviewing how traditional assessment approaches can accommodate people who are new to credit or have successfully recovered from earlier financial challenges.
Financial education as part of inclusion
FNB believes financial inclusion should be measured not only by the number of people who gain access to financial products, but also by whether customers understand how those products work.
This includes helping customers understand the cost of borrowing, repayment obligations, the impact of their repayment behaviour on their credit profiles and what borrowing levels are appropriate for their individual circumstances.
“Customers should leave the process with more than a credit facility. They should leave with a better understanding of how credit works, what it costs and how to manage it responsibly.”
For FNB, this philosophy informs the design of credit products aimed at consumers building or rebuilding their credit profiles, with structured limits and guidance intended to provide an opportunity to establish responsible repayment patterns.
The bank also views credit as one element of a broader financial journey that can include saving, protection, transactional banking and longer-term financial planning.
Different customers, different starting points
South Africa’s socio-economic landscape means consumers enter the formal financial system with varying levels of financial experience, knowledge and exposure to credit.
For some, understanding how credit works may have been learned through family or personal experience. For others, the formal credit system may be unfamiliar.
Tshabalala argues that financial information should therefore be accessible rather than treated as specialist knowledge.
“Not everyone starts from the same financial position. Many South Africans have not had the benefit of learning about credit and financial products through family experience or exposure.”
He adds:
“If we’re inviting more people into the formal credit system, the rules of that system should not feel like privileged knowledge. Customers deserve information that is clear, practical and easy to understand.”
While financial education cannot resolve structural challenges such as unemployment, income pressures and rising living costs, FNB says clearer information can help consumers navigate financial decisions with greater confidence.
Credit as a long-term financial asset
Tshabalala says a customer’s first credit facility can have implications well beyond the initial borrowing decision.
A history of consistent repayments and responsible credit management can contribute to a stronger credit profile over time, potentially supporting access to future financial products and opportunities, subject to affordability and lending assessments.
“A first credit product may seem small, but the track record built through it can influence future opportunities over time.”
He says the responsibility of financial institutions therefore extends beyond determining whether a customer qualifies at a particular point in time.
“We must also help customers understand that a good credit record is an important financial asset.”
Moving financial inclusion forward
As South Africa’s financial inclusion agenda evolves, the debate is increasingly shifting from access alone to meaningful and responsible participation.
For FNB, creating appropriate pathways into credit, combined with financial education and responsible lending practices, can help customers develop stronger financial habits while gaining experience in managing formal credit.
Ultimately, the bank says, responsible borrowing should form part of a broader approach to financial resilience rather than becoming an end in itself.
“When supported by responsible borrowing habits and sound financial decision-making, credit can also contribute to greater financial resilience and long-term financial wellbeing,” Tshabalala concludes.
The message from FNB is therefore clear: expanding credit access and protecting consumers do not have to be competing objectives. With appropriate affordability assessments, structured credit, transparent information and practical guidance, the transition into — or back into — the formal credit market can become part of a longer-term journey towards greater financial capability.
#FNB #ThabisoTshabalala #ResponsibleCredit #FinancialWellbeing #FinancialLiteracy #CreditJourney #SmartMoney