
Retailers face rising working-capital demands as volatile fuel prices, changing consumer behaviour and the EV transition reshape the economics of the forecourt
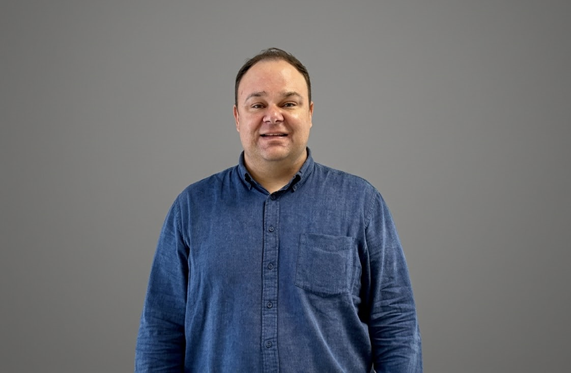
Seen Here: Morné Rossouw, Franchise Specialist at FNB, highlights the growing pressure fuel-price volatility is placing on South Africa’s forecourts, with working-capital resilience, diversification and adaptability emerging as critical to sustaining profitability in a rapidly changing retail environment. Photo Credit: Supplied
JOHANNESBURG, 8 September 2026 — South Africa’s fuel retailers are facing a new operating reality in which fuel-price volatility is no longer simply a short-term disruption, but an increasingly structural challenge to working capital, stock management and long-term business resilience.
For motorists, sharp movements in the price of petrol and diesel are immediately visible at the pump. For fuel retailers, however, the more pressing issue can be what it costs to replenish their tanks and maintain adequate stock levels when prices rise rapidly.
According to Morné Rossouw, Franchise Specialist at FNB, retailers operating in a regulated-margin environment do not automatically benefit from higher pump prices through increased margins per litre.
Instead, a significant fuel-price increase can substantially increase the amount of capital required to maintain normal inventory levels.
“A fuel delivery that cost R2 million a few weeks earlier could suddenly require hundreds of thousands of rands more,” Rossouw explains, highlighting the liquidity pressure created when retailers need to fund larger stock purchases while continuing to meet their other operating obligations.
The consequence is a delicate balancing act: retailers need sufficient fuel to avoid running dry, but simultaneously need to manage cash flow carefully in an environment where market conditions can change rapidly.
Working capital becomes a strategic issue
The challenge is particularly acute because fuel retailers must coordinate stock levels, delivery schedules, payment obligations and price movements, often within compressed timeframes.
A conventional funding facility based largely on historical fuel prices and sales volumes may therefore become less effective when the cost of replenishing stock increases sharply.
Rossouw argues that retailers need funding solutions capable of responding to temporary spikes in capital requirements without leaving businesses structurally overfunded once prices normalise.
FNB Business’s spike pricing offering, for example, is designed to provide additional short-term working-capital support when significant fuel-price increases place pressure on a retailer’s stock funding requirements.
The broader principle is one of financial flexibility: viable businesses should be able to access additional liquidity when market conditions temporarily increase their funding needs, while retaining an appropriate capital structure once conditions stabilise.
For the fuel-retail industry, this makes the relationship between retailers, franchisors, fuel companies and financial institutions increasingly important.
The forecourt can no longer rely on fuel alone
While working-capital management can help retailers navigate price volatility, financial resilience increasingly depends on what happens beyond the fuel pump.
Fuel remains the core product, but constrained margins mean retailers are looking for additional sources of revenue and profitability.
Convenience stores, quick-service restaurants, coffee outlets, car washes, courier services and other value-added services are becoming increasingly important components of the modern forecourt proposition.
This reflects a fundamental change in consumer behaviour.
Historically, the primary reason for visiting a filling station was to refuel, with additional purchases largely incidental. Increasingly, customers are choosing destinations based on the broader experience and range of services available — with fuel becoming one component of the overall proposition.
A motorist may stop because a site offers quality coffee, groceries or prepared food and refuel during the same visit.
For retailers, that shift presents an opportunity to increase customer spend without relying exclusively on fuel volumes.
Diversification could strengthen profitability
The changing economics of the forecourt sector also have implications for how individual sites are assessed by investors and funders.
A site with multiple revenue streams may be better positioned to withstand fluctuations in fuel demand, changing mobility patterns and broader economic disruption than a business whose performance is overwhelmingly dependent on fuel sales.
Location, retail performance, tenant quality, customer traffic and the strength of non-fuel offerings are therefore becoming increasingly important indicators of long-term commercial value.
This does not mean that every filling station should attempt to become a large destination retail centre.
A rural forecourt, a filling station in a smaller town and a high-volume transit site may each require very different strategies based on their customer base, available space, ownership structure and local economics.
The underlying principle, however, remains consistent: adaptability is becoming a critical component of forecourt resilience.
Preparing for the electric-vehicle transition
The evolution of the sector is also being shaped by the gradual emergence of electric vehicles.
Although EV adoption is unlikely to displace South Africa’s internal-combustion vehicle fleet overnight, retailers face a strategic decision about how their sites will accommodate changing mobility patterns.
Rather than viewing charging infrastructure solely as a threat to traditional fuel sales, forecourt operators could regard it as an opportunity to rethink the customer journey.
Charging typically requires more time than conventional refuelling, potentially creating additional opportunities for customers to shop, eat, work or access other services while their vehicles charge.
This could further strengthen the commercial case for diversified forecourts, particularly at strategically located sites with sufficient space and customer demand.
Resilience beyond the pump
For South Africa’s fuel retailers, the next phase of the industry will require more than simply responding to changes in the pump price.
Geopolitical tensions, international oil prices, currency movements and supply-chain disruptions remain external factors that individual retailers cannot control.
What businesses can control is their preparedness.
That means maintaining appropriate working-capital capacity, understanding the timing and scale of stock requirements, strengthening relationships across the fuel-retail ecosystem and developing complementary revenue streams that can support profitability when fuel economics come under pressure.
The forecourt of the future is therefore likely to be defined less by the number of litres it sells and increasingly by the strength of the overall business model behind the pumps.
As Rossouw puts it, retailers cannot determine what happens in global energy markets. They can, however, determine how effectively their businesses respond when volatility arrives.
In an industry where the price at the pump can change overnight, resilience may ultimately depend on building a business that is about far more than fuel.